Jul 25th, 2025

How Much Can Alfred Borrow for a Home Loan in 2025? Detailed Breakdown

Embedded Overview Image

How Much Can Alfred Borrow for a Home Loan in 2025? Detailed Breakdown

Alfred and Reena have a combined gross income of $266,400 per year and support two children. With existing debts—a $990,000 mortgage and a car loan costing $1,100 per month—they’re exploring their capacity for an additional home loan in 2025.


Financial Planning for Home Loan

Financial Summary

  • Combined Gross Income: $266,400
  • Estimated Net Income: ~$190,000/year (~$15,833/month)
  • Liabilities:
    • Mortgage balance: $990,000
    • Car loan payments: $1,100/month (~$13,200/year)
    • Credit cards: $14,000 limit, currently zero balance
  • Living Costs (Family of 4): ~$3,500/month (~$42,000/year)
  • Existing Debt-to-Income Ratio: ~$1.03M ÷ $266,400 ≈ 3.9×

Bank Lending Criteria Snapshot

  • DTI Limit: Typically 6–8× gross income → max total debt ~$1.6M–$2.1M
  • Stress-Test Rate: Banks often assess repayments at 8–9% interest
  • Net Income Surplus: ~$62,800/year available for new loan repayments
Family Budgeting for Borrowing Power

Borrowing Power Estimate

  • Estimated Maximum New Loan: $450,000–$550,000
  • Total Borrowing Capacity: ~$1.5M–$1.6M (aligned with DTI limits)

Challenges & Opportunities

  • No liquid savings may concern some lenders.
  • Dependents increase living costs, slightly reducing capacity.
  • Strong income and clean repayment history are positives.

Recommendations

  1. Build a modest savings cushion to strengthen your application.
  2. Engage a mortgage broker to compare lenders—some permit DTI above 6×.
  3. Review actual living expenses; lower costs can boost loan capacity.
  4. Consider consolidating or refinancing existing debt to improve serviceability.

Ready to explore your options? Chat with a loan specialist now to assess your borrowing power and streamline your next move.
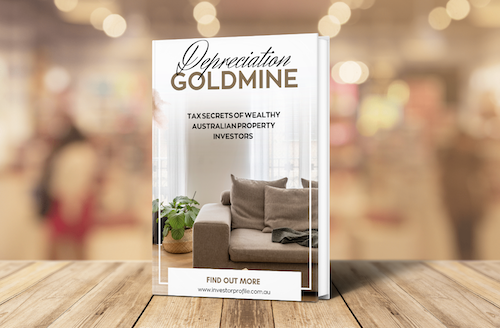
Depreciation Guide

Discover the #1 tax secret wealthy Australian property investors use to grow their portfolios faster — even in a high interest rate environment.

  • Learn how to turn wear and tear into wealth
  • See real examples of $15,000+ first-year deductions
  • Understand how to structure your purchases for maximum after-tax ROI

Download Your Free Wealth Building Guide

This ebook reveals how to legally slash your tax bill while building long-term wealth through property. Learn the strategies savvy investors use to gain an edge — even before settlement.

  • Maximise tax deductions and improve cash flow
  • Understand Division 40 vs 43 and how to claim both
  • Position yourself to reinvest and scale faster
Free Instant Access
@

Snowcation? Smart investors see more than powder and pine trees. They’re buying in high-demand holiday towns—where tourists pay top dollar and properties work year-round. Think: • High nightly Air...

@

Everyone wants the dream lifestyle — but few build it the right way. It’s not about luxury cars or beach views. It’s about income-producing assets, not liabilities. Run the numbers. Use leverage wisel...

@

A rooftop infinity pool. Imported stone. Twelve-foot pivot door. This isn’t a renovation — it’s a statement. The kind of place the wealthy retreat to while you’re still scrolling listings. #creators...

You may also like

Related posts

How to Finance an Apartment Block: Comprehensive Guide for 2025

2025 Guide to Financing Multifamily Properties Securing funding for an apartment block—defined as a multifamily property with five or more units—requires a different approach than traditional residential home loans. In 2025, various commercial real estate lending options and strategies have emerged to help investors navigate this complex financing landscape. Popular...

May 14th, 2025
1 year ago
DTI Impact of Adding a Third Investment Property

Impact of Debt-to-Income Ratio in Real Estate Investments Debt-to-Income Ratio (DTI) measures a borrower’s capacity to handle monthly payments and repay debts. It is especially important when expanding a real estate portfolio by adding more investment properties. This article examines how adding a third property can affect your DTI and...

Jun 7th, 2025
1 year ago
The Six-Year Rule: How to Maintain CGT Exemption on Your Former Home

A Refresher on the Six-Year CGT Exemption Rule When you leave your primary home and decide to rent it out, you might still enjoy a complete Capital Gains Tax (CGT) exemption when it’s time to sell—all thanks to the six-year rule. This provision offers property owners flexibility, ensuring that even...

May 6th, 2025
1 year ago
Straightforward process

Ready to take control of your financial future?

01
Discovery Q&A:

We begin with a personalized discovery Q&A to understand your goals, risk tolerance, and financial situation.

02
Custom Strategy:

Based on your needs, we craft a strategic investment or financial plan tailored just for you.

03
Ongoing Support:

We help you track progress, optimize decisions, and adjust your plan as your life and markets evolve.

04
Financial Freedom:

With a clear roadmap and expert guidance, you move confidently toward long-term wealth and peace of mind.

28+ Years guiding investors
Plan Your Investment Strategy

Understand your goals and build a tailored strategy—whether you're focused on cashflow, capital growth, or long-term wealth creation.

Access the Right Opportunities

Explore high-growth areas, new builds, house & land packages, or SMSF-ready properties matched to your financial profile.

Build Long-Term Wealth

Leverage tax advantages, depreciation, and smart lending strategies to maximise returns and grow your portfolio sustainably.

Start Your Investment Journey

Smart Property Investing Starts Here

Whether you're a first-time investor or growing your portfolio, we provide the guidance, tools, and insights you need to make informed decisions and secure high-performing properties. Let us help you turn property into prosperity.