A Refresher on the Six-Year CGT Exemption Rule
When you leave your primary home and decide to rent it out, you might still enjoy a complete Capital Gains Tax (CGT) exemption when it’s time to sell—all thanks to the six-year rule. This provision offers property owners flexibility, ensuring that even if you temporarily move away, your tax benefits can remain intact.
What Does the Six-Year Rule Entail?
The six-year rule permits you to treat your former main residence as your principal home for CGT purposes for up to six years after moving out and renting the property—under the conditions that:
- The home was your actual main residence before it was let out.
- You do not designate another property as your main residence at the same time (with one notable exception explained later).

Lifestyle Flexibility: Living in Other Rentals
It’s perfectly fine to reside in various rental properties during these six years. The crucial point is:
You must avoid claiming any other property as your main residence for CGT purposes.
As long as you adhere to this rule, your original home continues to enjoy a full CGT exemption for up to six years—even while it’s rented out.
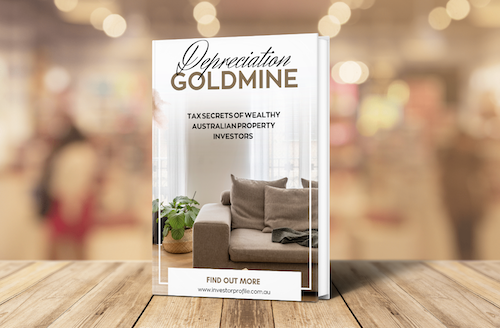
Discover the #1 tax secret wealthy Australian property investors use to grow their portfolios faster — even in a high interest rate environment.
- Learn how to turn wear and tear into wealth
- See real examples of $15,000+ first-year deductions
- Understand how to structure your purchases for maximum after-tax ROI
Download Your Free Wealth Building Guide
This ebook reveals how to legally slash your tax bill while building long-term wealth through property. Learn the strategies savvy investors use to gain an edge — even before settlement.
- Maximise tax deductions and improve cash flow
- Understand Division 40 vs 43 and how to claim both
- Position yourself to reinvest and scale faster
Purchasing a New Home: How It Affects Your CGT
Should you buy and move into a different property, you face a decision: which residence will be declared your main home? The rules ensure that you cannot have the CGT exemption applied to two properties simultaneously. There is, however, a small leeway—a six‐month overlap allowed by the ATO under genuine moving circumstances.

Real-Life Example
Consider Jane, who left her Sydney apartment in 2020 and started renting it out. For the next five years, she lived in various rental homes in Melbourne and Brisbane without purchasing another property. When Jane finally sold her Sydney apartment in 2025, she successfully qualified for the full CGT exemption under the six-year rule—since she never claimed any other main residence during that period.
Restarting the Six-Year Countdown
If you decide to move back into your previous home—even if only briefly—the six-year period resets. This means you may potentially benefit from the rule again should you choose to rent it out in the future.
Exceeding the Six-Year Limit
Renting out your property beyond the six-year window means that CGT will be applicable for the period exceeding the exemption. Keeping detailed records is crucial to accurately determine any tax liability.
Overview of Key Points
| Action | Impact on CGT |
|---|---|
| Renting your main residence for under six years | Fully exempt, if no other property is claimed as the main residence |
| Residing in other rental accommodations | Permissible without affecting the exemption |
| Buying and declaring a new main residence | Must choose one residence – potential partial CGT may apply |
| Returning to your original home | Resets the six-year rule |
| Renting the property for more than six years | CGT applies for the period exceeding six years |
Final Thoughts
The six-year rule is a valuable tool for property owners looking to maximize tax benefits while navigating housing transitions. However, its advantages come with strict conditions. For tailored advice and to ensure you remain compliant, it’s wise to consult a property tax specialist.
Need to assess your CGT situation? Chat with our team for personalized guidance.