Introduction
Australia’s financial sector operates under a strict regulatory framework, especially in lending. Credit exposure limits are a key tool banks use to manage risk, and they have a profound effect on real estate lending—a major component of the Australian economy.
Key Points
- Banks set credit exposure caps for individual borrowers and industry sectors (e.g., real estate) to control risk.
- Surpassing these limits can restrict additional borrowing, particularly with high concentration in one sector.
- APRA’s Prudential Standard APS 221 mandates sound credit concentration practices, with sector‐based flexibility.

Understanding Credit Exposure Limits
Credit exposure limits are ceilings banks impose on how much they can lend to a single borrower or invest in a given sector. They help avoid over-concentration of risk. For example, with a $1 million limit, a borrower with $500 000 outstanding can only obtain an additional $500 000, subject to serviceability.
Factors Influencing Credit Exposure Limits
- Income and Expenses: Borrower repayment capacity is a primary determinant.
- Creditworthiness: Assessed via credit scores, repayment history and overall financial health.
- Sectoral Risk Analysis: Banks evaluate industry risk and adjust exposure caps accordingly.
Sector-Specific Credit Exposure Limits
The Australian Prudential Regulation Authority (APRA) enforces exposure management under APS 221. Banks must monitor sectoral exposures—especially volatile markets like real estate and commercial property—and can be required to set tighter caps to preempt systemic risk.
Real Estate Lending Considerations
Real estate’s cyclical nature means banks apply rigorous credit assessments. Residential and commercial real estate often have different exposure tiers, reflecting varying risk profiles.
Risk of Concentrated Investments
Heavy investment in one sector can quickly hit exposure ceilings. For instance, borrowers with over $1.5 million in real estate financing may face stricter lending terms, including detailed documentation or outright credit refusal.
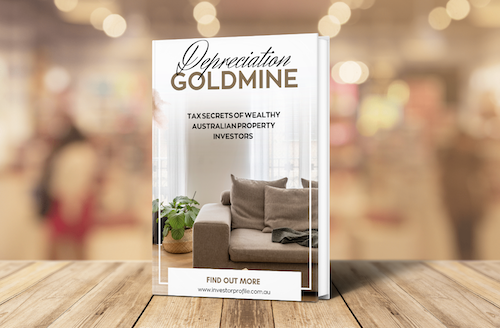
Discover the #1 tax secret wealthy Australian property investors use to grow their portfolios faster — even in a high interest rate environment.
- Learn how to turn wear and tear into wealth
- See real examples of $15,000+ first-year deductions
- Understand how to structure your purchases for maximum after-tax ROI
Download Your Free Wealth Building Guide
This ebook reveals how to legally slash your tax bill while building long-term wealth through property. Learn the strategies savvy investors use to gain an edge — even before settlement.
- Maximise tax deductions and improve cash flow
- Understand Division 40 vs 43 and how to claim both
- Position yourself to reinvest and scale faster
Striking a Balance
- Diversify across asset classes to spread risk.
- Reduce existing debt where feasible.
- Maintain strong, consistent income records.
- Explore lenders with different exposure policies.
Regulatory Overview
Prudential Standard APS 221 outlines large-exposure management. Key thresholds include defining any single exposure ≥10% of Tier 1 Capital as “large,” and capping aggregated large exposures at 25% of Tier 1 Capital.
Separate limits apply to foreign governments, systemically important banks and other sectors to mitigate concentration risk.

Risk Mitigation Strategies
- Investment Diversification: Broadening portfolios reduces dependency on a single sector.
- Debt Management: Lower balances improve borrowing capacity and creditworthiness.
- Income Stability: Consistent income histories strengthen loan applications.
- Alternative Lenders: Different institutions have varied exposure rules—shop around.
Comparative Exposure Limits Table
| Exposure Type | Limit (% of Tier 1 Capital) | Notes |
|---|---|---|
| Aggregate Exposures | ≤25% | General cap per APS 221 |
| Foreign Governments (0% risk-weight) | ≤50% | Classified under APS 112 risk categories |
| D-SIB ADIs | ≤20% | Inter-bank limit for systemically important banks |
| Sector Limits | Case-by-case | APRA may impose stricter rules |
Conclusion
Credit exposure limits underpin prudent risk management in Australian banking, especially for real estate lending. APRA’s enforcement of APS 221 ensures robust sectoral safeguards and protects the economy from concentrated vulnerabilities. Borrowers should diversify, manage debt carefully, and maintain solid documentation to navigate these limits effectively.
For more insights on real estate investing and exposure management, visit Investor Profile.