Aug 30th, 2025

How Much Can I Borrow? Estimating Your Loan Capacity in 2025

Loan Capacity Overview

How Much Can I Borrow? Estimating Your Loan Capacity in 2025

Before you start house–hunting or eye that next investment property in Australia, you need to know how much a lender will let you borrow. In 2025, banks and other financiers will closely examine your income, living expenses, existing debts, number of dependents and their internal lending rules—this includes debt-to-income (DTI) limits, interest-rate buffers and serviceability benchmarks.

Key Financial Factors Considered by Lenders

  • Gross Salary: Your taxable income is the cornerstone. A full-time worker on $75,000 per year is a common example.
  • Government Benefits: Family Tax Benefit A & B (for example, $7,500 annually) may be partly or fully included in your serviceability assessment.
  • Dependents: Two children will raise your assumed living costs, trimming your available loan buffer.
  • Assets & Liabilities:
    • A primary home worth $440,000 with a $259,000 mortgage.
    • Weekly repayments of $625 (about $32,500 per year), though lenders often apply a minimum of $1,170 per month when calculating capacity.
    • $30,000 in savings and $26,000 in redraw—useful for deposits but not directly boosting borrowing power.
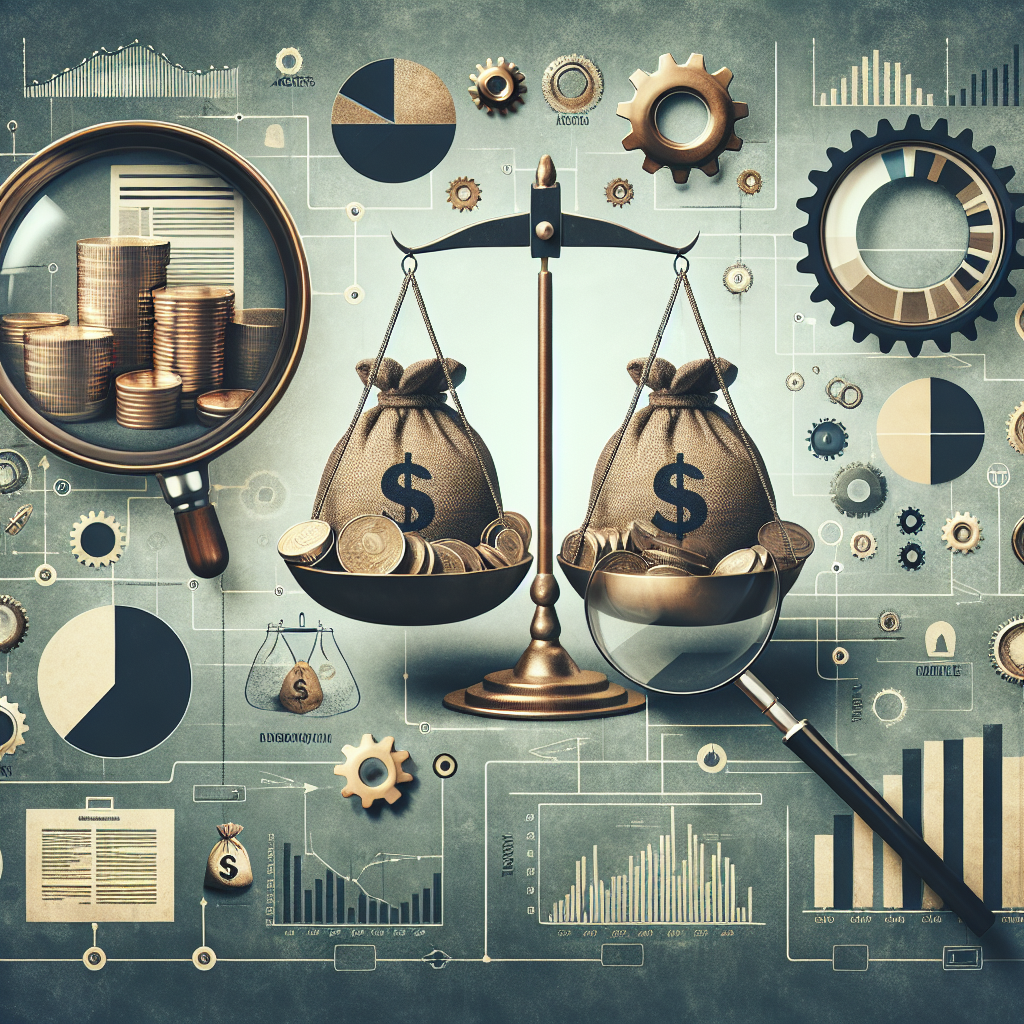
Financial Factors for Borrowing Capacity

Estimating Your Borrowing Capacity

Lenders use conservative “assessment rates” to guard against future rate rises. Even if your loan has a 6% interest rate, they may test your repayments at 9%.

Calculation Snapshot:

  • Total assessable income: $75,000 (salary) + $7,500 (FTB) = $82,500 per year.
  • Monthly after-tax income + FTB: Approximately $5,500.
  • Estimated living costs (based on HEM): $3,200 per month.
  • Surplus for loan servicing: ~$1,138 monthly.

At a 9% assessment rate over 30 years, that buffer equates to a borrowing capacity of around $141,400.

Impact of Other Factors

  • DTI Limits: Many lenders cap total debt at 6× income. On $82,500 annual income, that’s $495,000 maximum debt. Subtract your $259,000 mortgage and you’d have room for ~$236,000—but strict serviceability rules often reduce that further.
  • LVR & Deposit: With $30,000 in savings, you could target properties up to roughly $170,000–$175,000, depending on your lender’s maximum LVR.

Tips to Boost Your Borrowing Capacity

  • Limit discretionary expenses to lower assessed costs.
  • Increase income via side gigs or rental returns.
  • Pay down existing debts.
  • Consider a joint application if you have a partner or family member.

Final Thoughts

Based on standard expenses, no additional debts and a conservative stress-test rate, your borrowing capacity in 2025 is roughly $141,400. For a precise assessment using lender-specific calculators, speak with a mortgage specialist.
Depreciation Guide

Discover the #1 tax secret wealthy Australian property investors use to grow their portfolios faster — even in a high interest rate environment.

  • Learn how to turn wear and tear into wealth
  • See real examples of $15,000+ first-year deductions
  • Understand how to structure your purchases for maximum after-tax ROI

Download Your Free Wealth Building Guide

This ebook reveals how to legally slash your tax bill while building long-term wealth through property. Learn the strategies savvy investors use to gain an edge — even before settlement.

  • Maximise tax deductions and improve cash flow
  • Understand Division 40 vs 43 and how to claim both
  • Position yourself to reinvest and scale faster
Free Instant Access

If you’d like tailored guidance or want to explore strategies to improve your borrowing power, contact our property finance team for expert advice.
@

6 properties before you’re 40. Full stop. No lottery win. No rich parents. Just strategy. Buy smart. Rent it out. Refinance. Repeat. Started with 1 deal in my 20s. Learned how to stack income, use e...

@

Still waiting for a sign to invest in property? Jesus fed the 5,000 — but He didn’t hand out investment portfolios. The wealthy aren’t waiting for miracles. They’re claiming deductions, leveraging e...

@

They don’t just buy homes — they claim the high ground. Hilltop retreats with panoramic views, passive income, and capital growth. While others chase lifestyle, the wealthy leverage it. Own the mount...

You may also like

Related posts

How Having Dependents Affects Your Home Loan Borrowing Power in Australia

How Dependents Impact Your Borrowing Capacity for a Mortgage in Australia When applying for a mortgage in Australia, the number of dependents—children or family members you financially support—can have a significant effect on the amount you can borrow. Lenders weigh your income, living expenses and existing liabilities to determine your...

Jul 22nd, 2025
1 year ago
Claiming Lenders Mortgage Insurance (LMI) as a Tax Deduction for Investment Properties in Australia (2025 Guide)

Understanding Lenders Mortgage Insurance in Australia In Australia, Lenders Mortgage Insurance (LMI) is a one-off premium typically required when borrowing over 80% of a property's value. When it comes to investment properties, LMI may be tax-deductible as a borrowing expense if you meet specific criteria. Tax Deduction Eligibility The Australian...

May 16th, 2025
1 year ago
How Much Can Peter Borrow for a Home in Adelaide?

Estimating Peter’s Borrowing Power in Adelaide (2025) When Peter sits down to apply for a home loan in Adelaide, lenders will review his salary, outgoings, debts and family responsibilities. Based on his details, here’s a realistic range of what he might borrow this year. Financial Snapshot Gross Income: $132,000 PAYG...

Aug 6th, 2025
1 year ago
Straightforward process

Ready to take control of your financial future?

01
Discovery Q&A:

We begin with a personalized discovery Q&A to understand your goals, risk tolerance, and financial situation.

02
Custom Strategy:

Based on your needs, we craft a strategic investment or financial plan tailored just for you.

03
Ongoing Support:

We help you track progress, optimize decisions, and adjust your plan as your life and markets evolve.

04
Financial Freedom:

With a clear roadmap and expert guidance, you move confidently toward long-term wealth and peace of mind.

28+ Years guiding investors
Plan Your Investment Strategy

Understand your goals and build a tailored strategy—whether you're focused on cashflow, capital growth, or long-term wealth creation.

Access the Right Opportunities

Explore high-growth areas, new builds, house & land packages, or SMSF-ready properties matched to your financial profile.

Build Long-Term Wealth

Leverage tax advantages, depreciation, and smart lending strategies to maximise returns and grow your portfolio sustainably.

Start Your Investment Journey

Smart Property Investing Starts Here

Whether you're a first-time investor or growing your portfolio, we provide the guidance, tools, and insights you need to make informed decisions and secure high-performing properties. Let us help you turn property into prosperity.