Jul 23rd, 2025

Understanding Expenses and Debt-to-Income (DTI) Ratios in Australian Mortgage Applications

Mortgage Expenses Overview

How Lenders Evaluate Expenses and Debts in Australian Home Loans

When you apply for a mortgage in Australia, lenders don’t just look at your salary. They’ll also assess your living expenses and existing debts to determine how much you can borrow and whether you qualify for a home loan.

Key Expense Categories

1. Household Expenditure Measure (HEM)

The HEM is a standardized benchmark that estimates minimum living costs based on:

  • Household size
  • Income level
  • Location
  • Number of dependents

Many lenders use the HEM instead of asking you to detail every expense. For example, a single applicant with three dependents might have a monthly HEM of around $4,800—even if their actual spend is lower.

Household Expenditure Measure (HEM)

2. Existing Loan Repayments

All current obligations count, including:

  • Mortgages
  • Car loans
  • Personal loans
  • Any other scheduled repayments

Lenders will see how these debts sit alongside the new home loan.
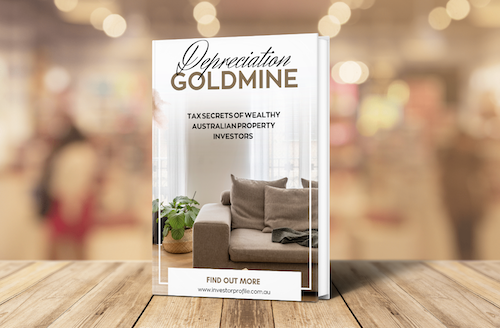
Depreciation Guide

Discover the #1 tax secret wealthy Australian property investors use to grow their portfolios faster — even in a high interest rate environment.

  • Learn how to turn wear and tear into wealth
  • See real examples of $15,000+ first-year deductions
  • Understand how to structure your purchases for maximum after-tax ROI

Download Your Free Wealth Building Guide

This ebook reveals how to legally slash your tax bill while building long-term wealth through property. Learn the strategies savvy investors use to gain an edge — even before settlement.

  • Maximise tax deductions and improve cash flow
  • Understand Division 40 vs 43 and how to claim both
  • Position yourself to reinvest and scale faster
Free Instant Access

3. Credit Card Limits

Even if your balance is low, lenders typically assume you’ll pay 3–5% of your total credit limit each month. A $16,000 limit could add about $480/month to your outgoings.

4. HECS/HELP Obligations

Higher Education Loan Program (HELP) debts trigger annual repayments once you earn above the threshold, reducing your net income and borrowing capacity.

5. Other Regular Costs

Additional recurring expenses include:

  • Private school fees
  • Childcare
  • Rent (if you still rent)
  • Insurance premiums

Debt-to-Income (DTI) Ratio

The DTI ratio divides your total liabilities by your gross income. Most Australian lenders cap this at around 6:1.
Debt-to-Income Ratio Illustration

For example, if your annual income is $100,000, your total debts shouldn’t exceed $600,000. If you already owe $450,000, you could borrow up to $150,000 more—subject to your cash flow and expense profile.

Tips to Strengthen Your Application

  • Pay down existing debts such as personal or car loans.
  • Reduce or cancel unused credit cards to lower assumed repayments.
  • Boost your income through overtime, a side gig, or adding another applicant.
  • Shop around for lenders who accept your actual expenses instead of using the HEM.

Understanding how lenders view your financial commitments can help you maximise your borrowing power and increase your chances of home loan approval. For a tailored assessment and strategy, explore our financial planning consultation.

@

We’re not just talking about owning a mountain retreat — we’re talking about owning one that pays for itself and then some. Picture this: a newly built, architect-designed escape nestled in the hills....

@

Getting the wobbles? That moment when doubt creeps in, your vision blurs, and you question everything. But here’s the truth — growth isn’t supposed to feel stable. The path to success always shakes be...

@

Ready to dive into property investing? Not so fast! Learn these 5 crucial mistakes to avoid before you make your first move. From rushing in without research to neglecting diversification, these tips...

You may also like

Related posts

Borrowing Power Breakdown: Jennifer, George, and Jeremy’s Joint Investment Strategy

Investment Property Financing Snapshot Jennifer, her husband George and nephew Jeremy are exploring the purchase of an investment property in Queensland. Together they earn a gross annual income of $279,000, carry manageable debts and have $70,000 in savings. Based on their cashflow and the industry’s standard serviceability tests, their borrowing...

Jul 27th, 2025
1 year ago
How a $100K Salary Built a $1.8M Property Portfolio Over 17 Years

How a $100K Salary Transformed Into a $1.8M Property Portfolio in 17 Years In a market where strategic borrowing and disciplined saving can create life-changing opportunities, one investor turned a modest salary into a multi-million dollar property portfolio. This journey, marked by calculated moves and timely refinancing, showcases the impact...

May 5th, 2025
1 year ago
Understanding Expenses and Debt-to-Income (DTI) Ratios in Australian Mortgage Applications

How Lenders Evaluate Expenses and Debts in Australian Home Loans When you apply for a mortgage in Australia, lenders don’t just look at your salary. They’ll also assess your living expenses and existing debts to determine how much you can borrow and whether you qualify for a home loan. Key...

Jul 23rd, 2025
1 year ago
Straightforward process

Ready to take control of your financial future?

01
Discovery Q&A:

We begin with a personalized discovery Q&A to understand your goals, risk tolerance, and financial situation.

02
Custom Strategy:

Based on your needs, we craft a strategic investment or financial plan tailored just for you.

03
Ongoing Support:

We help you track progress, optimize decisions, and adjust your plan as your life and markets evolve.

04
Financial Freedom:

With a clear roadmap and expert guidance, you move confidently toward long-term wealth and peace of mind.

28+ Years guiding investors
Plan Your Investment Strategy

Understand your goals and build a tailored strategy—whether you're focused on cashflow, capital growth, or long-term wealth creation.

Access the Right Opportunities

Explore high-growth areas, new builds, house & land packages, or SMSF-ready properties matched to your financial profile.

Build Long-Term Wealth

Leverage tax advantages, depreciation, and smart lending strategies to maximise returns and grow your portfolio sustainably.

Start Your Investment Journey

Smart Property Investing Starts Here

Whether you're a first-time investor or growing your portfolio, we provide the guidance, tools, and insights you need to make informed decisions and secure high-performing properties. Let us help you turn property into prosperity.