Jun 6th, 2025

How Lenders Account for Rental Income Variability

Rental Property

Why Lenders Treat Rental Income as a Variable Stream

When you apply for a mortgage or refinance an investment property, lenders usually view rental income more cautiously than a regular salary. Because rent can fluctuate due to vacancies, upkeep and market shifts, most institutions apply a conservative discount and demand strong documentation.

Key Factors Lenders Consider

  • Vacancy Periods: No property maintains 100% occupancy. Any gap between tenants means zero rent while you still cover mortgage payments, insurance, utilities and maintenance. Even brief voids can strain cash flow and reduce overall returns.
  • Maintenance Costs: Landlords bear the expense of repairs and general upkeep—everything from landscaping and painting to appliance fixes and pest control. Because these outlays vary year to year, lenders often estimate maintenance at a flat percentage (for example, 1% of property value or 50% of gross rent).
  • Market Fluctuations: Economic downturns, changing neighbourhood supply, or shifts in tenant demand can push rental rates down. Lenders factor in local and national trends to gauge how secure your projected income really is.

How Lenders Adjust for Variability

  • Shading Rental Income: It’s common for lenders to count only 70–80% of your gross rent when calculating borrowing capacity. For instance, a $2,000/month lease might be valued at $1,400–$1,600 in their stress test to allow for voids, agent fees and unexpected costs.
  • Documentation Requirements: To verify your rental projections, expect to provide:
    • A signed lease agreement
    • Recent rent statements or bank records (typically 3–6 months’ worth)
    • Tax returns showing rental earnings (often 1–2 years of history)
    • If the property is vacant or newly acquired, a market appraisal from a licensed agent
  • Evidence of Consistency: A track record of steady rental receipts carries more weight than a brand new lease. While predicted income can be accepted with supporting appraisals or leases, actual deposits are always more persuasive.
  • Specialist Lenders: Some second-tier or niche lenders may accept up to 100% of rental income—but they often do so under stricter terms or higher interest rates.

Conclusion

Because rental revenue can ebb and flow, lenders apply a safety margin—discounting gross rent and enforcing robust proof of income. This approach ensures borrowers remain resilient against vacancies, surprise repairs or market downturns and helps prevent over-extension on their investment loans.
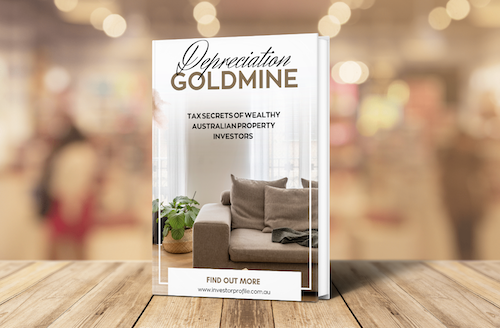
Depreciation Guide

Discover the #1 tax secret wealthy Australian property investors use to grow their portfolios faster — even in a high interest rate environment.

  • Learn how to turn wear and tear into wealth
  • See real examples of $15,000+ first-year deductions
  • Understand how to structure your purchases for maximum after-tax ROI

Download Your Free Wealth Building Guide

This ebook reveals how to legally slash your tax bill while building long-term wealth through property. Learn the strategies savvy investors use to gain an edge — even before settlement.

  • Maximise tax deductions and improve cash flow
  • Understand Division 40 vs 43 and how to claim both
  • Position yourself to reinvest and scale faster
Free Instant Access
@

6 properties before you’re 40. Full stop. No lottery win. No rich parents. Just strategy. Buy smart. Rent it out. Refinance. Repeat. Started with 1 deal in my 20s. Learned how to stack income, use e...

@

Luxury property isn’t just a dream — it’s a strategy. While others save, the wealthy structure deals, leverage assets, and stack equity. Comment ‘masterplan’ to get the blueprint they don’t teach you....

@

She cleaned up after 7 grown men… now she’s flipping cottages for capital gains. Snow White’s no longer waiting for Prince Charming — she’s using depreciation schedules, equity releases, and off-mar...

You may also like

Related posts

Victorian Vacant Residential Land Tax 2025: Key Changes and Deadlines

Victorian Vacant Residential Land Tax 2025: Key Changes and Deadlines From January 1, 2025, Victoria’s Vacant Residential Land Tax (VRLT) expands statewide. Any residential land left unoccupied for more than six months during 2024 will be subject to VRLT, not just properties in inner or middle Melbourne. Key Dates &...

Jun 15th, 2025
1 year ago
How Much Can Peter Borrow for a Home in Adelaide?

Estimating Peter’s Borrowing Power in Adelaide (2025) When Peter sits down to apply for a home loan in Adelaide, lenders will review his salary, outgoings, debts and family responsibilities. Based on his details, here’s a realistic range of what he might borrow this year. Financial Snapshot Gross Income: $132,000 PAYG...

Aug 6th, 2025
1 year ago
Using Property Depreciation to Fund Your Next Investment Purchase

Using Property Depreciation to Fund Your Next Investment Purchase Utilizing Depreciation as a Financial Strategy By claiming depreciation on your existing rental properties, you can lower your taxable income, boost cash flow and create a funding source for your next acquisition. This guide walks you through the steps to capture...

Jun 6th, 2025
1 year ago
Straightforward process

Ready to take control of your financial future?

01
Discovery Q&A:

We begin with a personalized discovery Q&A to understand your goals, risk tolerance, and financial situation.

02
Custom Strategy:

Based on your needs, we craft a strategic investment or financial plan tailored just for you.

03
Ongoing Support:

We help you track progress, optimize decisions, and adjust your plan as your life and markets evolve.

04
Financial Freedom:

With a clear roadmap and expert guidance, you move confidently toward long-term wealth and peace of mind.

28+ Years guiding investors
Plan Your Investment Strategy

Understand your goals and build a tailored strategy—whether you're focused on cashflow, capital growth, or long-term wealth creation.

Access the Right Opportunities

Explore high-growth areas, new builds, house & land packages, or SMSF-ready properties matched to your financial profile.

Build Long-Term Wealth

Leverage tax advantages, depreciation, and smart lending strategies to maximise returns and grow your portfolio sustainably.

Start Your Investment Journey

Smart Property Investing Starts Here

Whether you're a first-time investor or growing your portfolio, we provide the guidance, tools, and insights you need to make informed decisions and secure high-performing properties. Let us help you turn property into prosperity.